
What Is the Senior Private Debt Push Down Initiative Program


Bathroom Grab Bar Set

Bedside Commode Chair

Portable Wheelchair
The Senior Private Debt Push Down Initiative Program is a strategic financing framework designed to optimize capital structure in private equity and institutional investments. It allows senior debt to be “pushed down” to operating subsidiaries, improving leverage efficiency and risk management while enhancing returns for stakeholders.
Key Takeaways
- Definition: The Senior Private Debt Push Down Initiative Program refers to a financial strategy where senior debt obligations are transferred from a holding company to its operating subsidiaries to improve capital efficiency.
- Purpose: It aims to optimize leverage, reduce borrowing costs, and enhance returns on equity by aligning debt with cash-generating assets.
- Who Uses It: Primarily used by private equity firms, institutional investors, and large corporations managing complex capital structures.
- Benefits: Lower interest rates, improved credit profiles, better risk isolation, and increased flexibility in financing arrangements.
- Risks: Potential for increased financial strain on operating units, regulatory scrutiny, and complexity in restructuring.
- Implementation: Requires careful legal structuring, lender consent, and alignment with existing covenants and regulatory frameworks.
- Future Outlook: Growing in popularity due to rising interest rates and demand for efficient capital deployment in private markets.
📑 Table of Contents
- Introduction to the Senior Private Debt Push Down Initiative Program
- How the Senior Private Debt Push Down Initiative Program Works
- Benefits of the Senior Private Debt Push Down Initiative Program
- Risks and Challenges of the Program
- Who Should Consider the Senior Private Debt Push Down Initiative Program?
- Implementation Tips and Best Practices
- Future Outlook and Industry Trends
- Conclusion
Introduction to the Senior Private Debt Push Down Initiative Program
Imagine you’re running a large company with multiple subsidiaries—each generating steady cash flow but operating under a centralized holding structure. Now, picture this: the parent company has taken on significant senior debt to fund acquisitions or expansion. But here’s the catch—the operating units, which actually produce the revenue, aren’t directly responsible for servicing that debt. This creates a disconnect between cash generation and debt obligations, often leading to higher borrowing costs and inefficient capital use.
Enter the Senior Private Debt Push Down Initiative Program. This isn’t just another Wall Street buzzword—it’s a strategic financial maneuver designed to fix that very disconnect. By “pushing down” senior debt from the parent level to the operating subsidiaries, companies can align their liabilities more closely with the assets and cash flows that support them. The result? A more efficient capital structure, lower interest expenses, and stronger financial performance.
But why does this matter now more than ever? With rising interest rates and tighter credit markets, investors and lenders are demanding smarter, more transparent ways to manage risk and return. The Senior Private Debt Push Down Initiative Program offers a solution that benefits both borrowers and lenders by creating clearer accountability and improving creditworthiness at the operational level. Whether you’re an investor, a CFO, or just curious about modern finance, understanding this program is essential in today’s complex financial landscape.
How the Senior Private Debt Push Down Initiative Program Works
Visual guide about What Is the Senior Private Debt Push Down Initiative Program
Image source: static.toiimg.com
At its core, the Senior Private Debt Push Down Initiative Program involves restructuring existing debt obligations so that senior loans are transferred from a parent or holding company to one or more of its operating subsidiaries. This process is not as simple as flipping a switch—it requires careful planning, legal documentation, and coordination with lenders and stakeholders.
The Mechanics of Debt Push Down
The first step in implementing the program is identifying which subsidiaries have strong, predictable cash flows. These are typically the businesses that generate consistent revenue—think manufacturing plants, service providers, or subscription-based platforms. Once identified, the parent company negotiates with lenders to restructure the debt so that the operating units become the primary obligors.
This often involves creating new loan agreements at the subsidiary level, backed by the assets and cash flows of that specific business. The parent company may still provide guarantees or support, but the legal and financial responsibility shifts downward. This “push down” allows the subsidiary to borrow directly, often at more favorable terms because the lender can assess risk based on the actual performance of the business unit.
Legal and Structural Considerations
One of the biggest challenges in executing a debt push down is navigating the legal and regulatory landscape. Existing loan covenants may prohibit such transfers, requiring renegotiation with lenders. Additionally, tax implications must be carefully evaluated—debt restructuring can trigger taxable events or affect interest deductibility under local laws.
To mitigate these risks, companies often work with legal and financial advisors to draft new intercompany agreements, update security packages, and ensure compliance with securities regulations. In some cases, special purpose vehicles (SPVs) are created to isolate risk and streamline the transfer process.
Example: A Real-World Application
Let’s say a private equity firm owns a portfolio company with three operating units: a logistics arm, a software division, and a retail chain. The parent company originally borrowed $200 million in senior debt to acquire the business. Under the old structure, all three units contribute to servicing the debt, but none are directly liable.
With the Senior Private Debt Push Down Initiative Program, the firm restructures the debt so that the logistics arm takes on $80 million, the software division $70 million, and the retail chain $50 million—each backed by their respective assets and cash flows. Now, lenders can evaluate each unit independently, potentially offering lower interest rates due to clearer risk assessment. The parent company retains oversight but reduces its direct liability, improving its overall balance sheet.
Benefits of the Senior Private Debt Push Down Initiative Program
Visual guide about What Is the Senior Private Debt Push Down Initiative Program
Image source: tvscapital.in
The appeal of the Senior Private Debt Push Down Initiative Program lies in its ability to unlock value across multiple dimensions of a company’s financial operations. From cost savings to risk management, the benefits are both tangible and strategic.
Lower Borrowing Costs
One of the most immediate advantages is the potential for reduced interest expenses. When debt is pushed down to operating units with strong cash flows, lenders perceive lower risk. This often translates into better credit ratings and more favorable loan terms. For example, a subsidiary with consistent EBITDA margins may qualify for a lower interest rate than the parent company, which carries broader corporate risk.
In a rising rate environment, even a 50-basis-point reduction in interest can save millions over the life of a loan. These savings can be reinvested into growth initiatives, used to pay down debt faster, or returned to investors as dividends.
Improved Capital Efficiency
By aligning debt with the assets that generate revenue, companies can optimize their capital structure. This means less idle capital, better asset utilization, and higher returns on equity. Investors appreciate this clarity—knowing that each dollar of debt is backed by a specific, income-producing asset increases confidence in the company’s financial health.
Moreover, pushing down debt can free up capacity at the parent level. With less direct liability, the holding company may be able to take on new investments or pursue strategic acquisitions without overleveraging.
Enhanced Risk Isolation
Another key benefit is risk containment. If one operating unit faces financial difficulties—say, the retail chain struggles due to changing consumer habits—the impact is largely confined to that subsidiary. The parent company and other units are shielded from immediate default risk, as the debt is legally tied to the underperforming business.
This isolation is particularly valuable in diversified portfolios, where not all units perform equally. It allows management to address problems at the operational level without triggering cross-default clauses or destabilizing the entire organization.
Greater Flexibility in Financing
The program also increases flexibility in future financing decisions. Subsidiaries can now access capital markets independently, issue their own debt, or pursue asset-based lending. This decentralization empowers business units to respond quickly to opportunities without waiting for parent-level approval.
For private equity firms, this means faster exits. A well-structured subsidiary with its own debt profile can be sold more easily, as buyers can underwrite the business based on its standalone financials.
Stronger Investor Confidence
Finally, transparency breeds trust. When debt is clearly allocated and supported by operational performance, investors—whether equity holders or lenders—gain a clearer picture of risk and return. This can lead to higher valuations, better access to capital, and stronger relationships with stakeholders.
Risks and Challenges of the Program
Visual guide about What Is the Senior Private Debt Push Down Initiative Program
Image source: acuitykp.com
While the Senior Private Debt Push Down Initiative Program offers compelling benefits, it’s not without risks. Implementing such a strategy requires careful planning and awareness of potential pitfalls.
Increased Financial Pressure on Operating Units
One of the most significant risks is the burden placed on individual subsidiaries. While aligning debt with cash flow sounds logical, it can strain businesses that are already operating on thin margins. If a unit underperforms—due to market shifts, operational issues, or external shocks—it may struggle to meet its debt obligations, leading to default or restructuring.
For example, a manufacturing subsidiary pushed down with $50 million in debt may face cash flow issues if raw material costs spike or demand drops. Without the parent’s direct support, it could be forced into distress, affecting the entire portfolio.
Complexity in Restructuring
Restructuring debt across multiple entities is inherently complex. It requires coordination between legal, tax, and finance teams, as well as negotiations with multiple lenders. Each loan agreement may have different terms, covenants, and consent requirements, making the process time-consuming and costly.
In some cases, lenders may resist the change, especially if they prefer the security of a parent guarantee. Overcoming this resistance often involves offering concessions, such as higher interest rates or additional collateral.
Regulatory and Tax Implications
Tax authorities closely scrutinize debt push-down transactions, particularly when they involve intercompany loans or transfers of assets. Improper structuring can lead to challenges around transfer pricing, thin capitalization rules, or unintended tax liabilities.
For instance, if a subsidiary borrows from the parent at an above-market interest rate, tax authorities may disallow the deduction, increasing the effective cost of debt. Similarly, pushing down debt to a low-tax jurisdiction could trigger anti-avoidance rules.
Potential for Conflicts of Interest
There’s also the risk of misaligned incentives. Parent companies may push down more debt than a subsidiary can handle to improve their own balance sheet, putting operational units at risk. Lenders, on the other hand, may demand stricter covenants at the subsidiary level, limiting managerial flexibility.
Clear communication, independent valuations, and third-party oversight can help mitigate these conflicts and ensure fairness across stakeholders.
Who Should Consider the Senior Private Debt Push Down Initiative Program?
Not every company is a good candidate for this program. It’s best suited for organizations with specific characteristics and strategic goals.
Private Equity Firms
Private equity firms are among the most active users of the Senior Private Debt Push Down Initiative Program. They often acquire businesses with complex capital structures and seek to optimize leverage post-acquisition. By pushing down debt, they can improve returns on equity, reduce portfolio risk, and prepare assets for sale.
For example, a PE firm acquiring a healthcare services company might use the program to isolate debt in high-performing clinics, making the overall business more attractive to potential buyers.
Large Corporations with Diversified Operations
Multinational corporations with multiple business units can also benefit. Companies in industries like energy, telecommunications, or consumer goods often have subsidiaries with strong cash flows but centralized debt. Pushing down debt allows them to unlock value and improve financial reporting.
Institutions Seeking Capital Efficiency
Institutional investors, such as pension funds or insurance companies, may use the program when managing private credit portfolios. It allows them to structure investments with clearer risk-return profiles and better alignment with underlying assets.
When It’s Not the Right Fit
The program is less suitable for startups, highly leveraged companies, or businesses with volatile cash flows. It also requires a stable regulatory environment and cooperative lenders. Companies with weak governance or poor financial controls may find the added complexity overwhelming.
Implementation Tips and Best Practices
Successfully executing the Senior Private Debt Push Down Initiative Program requires more than just financial acumen—it demands strategic planning and disciplined execution.
Conduct a Thorough Financial Assessment
Before making any moves, analyze the cash flow stability, asset base, and creditworthiness of each operating unit. Use stress testing to simulate how subsidiaries would perform under adverse conditions. This helps determine the appropriate debt allocation and avoid over-leveraging.
Engage Stakeholders Early
Involve lenders, legal advisors, tax experts, and internal teams from the outset. Early communication builds trust and reduces resistance during negotiations. Present a clear business case that highlights benefits for all parties.
Structure for Flexibility
Design the debt push down to allow for future adjustments. Include provisions for refinancing, covenant relief, or debt reallocation if market conditions change. Flexibility is key to long-term success.
Monitor Performance Closely
Once implemented, establish robust monitoring systems to track subsidiary performance, debt service coverage, and covenant compliance. Regular reviews help identify issues early and allow for timely interventions.
Maintain Transparency
Keep investors and lenders informed about the program’s progress and outcomes. Transparent reporting builds credibility and supports future financing efforts.
Future Outlook and Industry Trends
The Senior Private Debt Push Down Initiative Program is gaining momentum as financial markets evolve. Several trends are driving its adoption.
Rising Interest Rates
With central banks tightening monetary policy, borrowing costs are increasing. Companies are seeking ways to reduce interest expenses, and debt push down offers a viable path. By securing better terms at the subsidiary level, firms can offset the impact of higher rates.
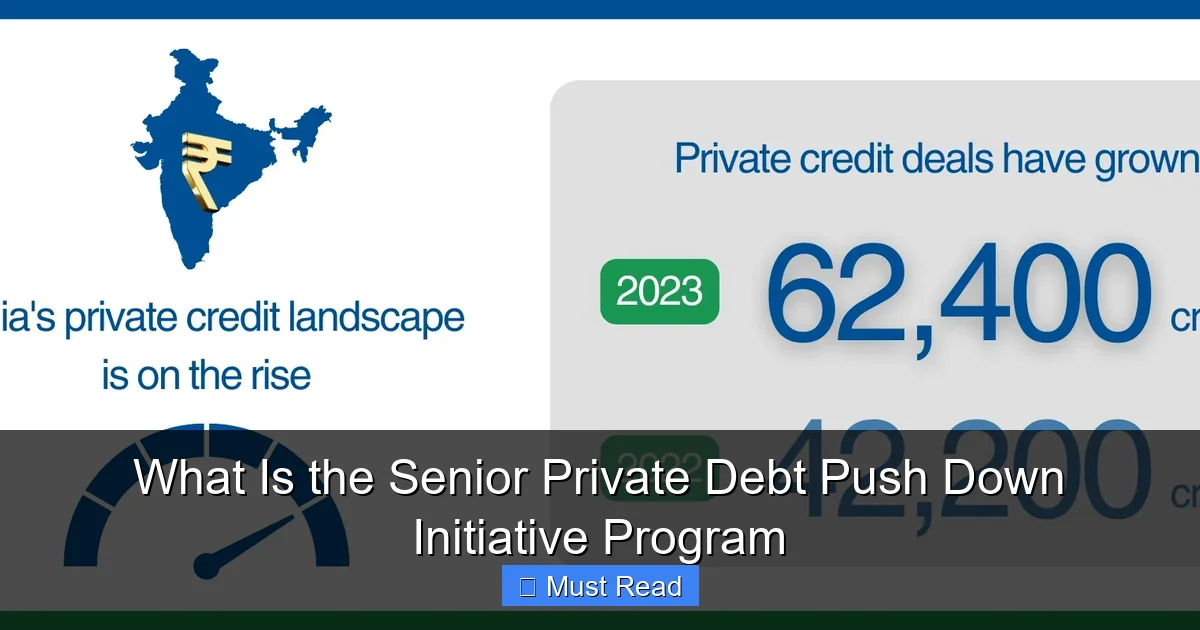
Growing Demand for Private Credit
The private credit market is expanding rapidly, with investors seeking higher yields outside traditional banking. The program aligns well with this trend, enabling structured, asset-backed lending that appeals to institutional investors.
Regulatory Scrutiny and Standardization
As the program becomes more common, regulators are paying closer attention. We may see new guidelines or reporting requirements to ensure transparency and prevent abuse. At the same time, industry groups are working to standardize best practices, making implementation smoother.
Technology and Data Analytics
Advances in financial modeling and data analytics are making it easier to assess subsidiary performance and optimize debt allocation. AI-driven tools can simulate thousands of scenarios, helping companies make smarter decisions.
Conclusion
The Senior Private Debt Push Down Initiative Program is more than a financial tactic—it’s a strategic evolution in how companies manage capital. By aligning debt with cash-generating assets, it creates a clearer, more efficient, and more resilient financial structure. For private equity firms, corporations, and institutional investors, it offers a powerful tool to enhance returns, reduce risk, and improve transparency.
However, success doesn’t come automatically. It requires careful planning, stakeholder alignment, and ongoing monitoring. When done right, the program can transform a company’s financial health and position it for long-term growth.
As markets continue to evolve, the demand for smarter, more transparent financing solutions will only increase. The Senior Private Debt Push Down Initiative Program is well-positioned to meet that demand—offering a blueprint for capital efficiency in an increasingly complex world.
Whether you’re evaluating an investment, managing a portfolio, or simply curious about modern finance, understanding this program is essential. It’s not just about moving debt around—it’s about building stronger, more sustainable businesses from the ground up.
Frequently Asked Questions
What is the main goal of the Senior Private Debt Push Down Initiative Program?
The main goal is to optimize a company’s capital structure by transferring senior debt from a parent company to its operating subsidiaries. This improves leverage efficiency, reduces borrowing costs, and aligns debt with the cash flows that support it.
Who typically uses this program?
Private equity firms, large corporations with multiple business units, and institutional investors are the primary users. They leverage the program to enhance returns, manage risk, and prepare assets for sale or refinancing.
Does pushing down debt reduce overall risk?
It can reduce risk at the parent level by isolating liabilities, but it may increase financial pressure on individual subsidiaries. Proper assessment and monitoring are essential to manage this trade-off.
Can any company implement this program?
No. It’s best suited for companies with stable, cash-generating subsidiaries and cooperative lenders. Startups or highly leveraged firms may find the complexity and risk too high.
What are the tax implications of a debt push down?
Tax implications vary by jurisdiction and structure. Improperly structured transactions can trigger challenges around interest deductibility, transfer pricing, or anti-avoidance rules. Professional tax advice is critical.
How does this program affect lenders?
Lenders may benefit from clearer risk assessment and stronger collateral, but they may also demand stricter covenants or higher rates if they perceive increased risk at the subsidiary level. Negotiation and transparency are key.