
Senior Debt Vs Mezzanine Debt


Electric Kettle with Auto Shutoff

Bedside Commode Chair

Kindle E-Reader
Senior debt is secured, lower-risk financing that lenders repay first in case of default, offering predictable interest rates and collateral protection. Mezzanine debt, while unsecured or subordinated, carries higher risk but allows for equity conversion and flexible terms, often used to fill funding gaps between senior debt and equity. Choosing between them depends on your company’s financial health, growth stage, and risk tolerance.
Key Takeaways
- Priority in repayment: Senior debt has first claim on assets and cash flow, making it safer for lenders, while mezzanine debt ranks below senior claims.
- Collateral requirements: Senior debt is typically secured by company assets; mezzanine debt may be unsecured or subordinated, increasing lender risk.
- Interest rates and costs: Senior debt offers lower interest due to security; mezzanine debt carries higher rates and often includes warrants or equity kickers.
- Flexibility and structure: Mezzanine debt provides more flexible terms and can convert to equity, appealing to growing companies seeking capital without dilution.
- Use cases: Senior debt suits stable businesses needing reliable funding; mezzanine debt fits expansion or refinancing when equity is limited.
- Impact on balance sheet: Senior debt appears as a traditional liability; mezzanine debt may be classified as equity if convertible, affecting financial ratios.
-
Risk profile: Lenders prefer senior debt for safety; investors in mezzanine debt expect higher returns for accepting greater default risk.
When it comes to raising capital for your business, understanding the different types of debt financing is crucial. Two common options are senior debt and mezzanine debt. While both provide funds to fuel growth, they differ significantly in structure, risk, cost, and purpose. Think of senior debt as the “first mortgage” on your business—secure and straightforward. Mezzanine debt, on the other hand, is like a second mortgage with added flexibility and potential upside, often used when traditional loans aren’t enough.
This guide breaks down everything you need to know about senior debt vs mezzanine debt, helping you choose the right path for your company’s financial strategy. Whether you’re a startup, mid-sized firm, or established enterprise, knowing when and how to use each type can make or break your capital-raising efforts.
Key Takeaways
- Understanding senior debt vs mezzanine debt: Provides essential knowledge
📑 Table of Contents
- What Is Senior Debt?
- What Is Mezzanine Debt?
- Key Differences Between Senior Debt and Mezzanine Debt
- When to Choose Senior Debt Over Mezzanine Debt
- When to Consider Mezzanine Debt
- Practical Tips for Structuring Your Financing Mix
- Real-World Examples: How Companies Use These Debt Types
- Common Misconceptions About Senior and Mezzanine Debt
- Conclusion: Making the Right Choice for Your Business
What Is Senior Debt?
Senior debt refers to loans or credit lines that rank highest in priority during repayment. In the event of bankruptcy or liquidation, senior lenders are paid first from the company’s assets. This makes senior debt one of the safest forms of borrowing for lenders, and consequently, one of the most affordable for borrowers.
These loans are typically secured by tangible assets such as real estate, equipment, inventory, or accounts receivable. Because the lender has a claim on specific collateral, the risk of loss is reduced. As a result, senior debt usually comes with lower interest rates compared to other forms of financing.
For example, a manufacturing company might use its factory buildings and machinery as collateral to secure a $10 million loan. If the business defaults, the bank can seize and sell those assets to recover its investment before any other creditors are considered.
Characteristics of Senior Debt
Senior debt stands out due to its clear hierarchy in repayment and strong legal protections. Let’s look at some defining features:
- First lien position: Senior lenders have the first legal right to assets pledged as collateral.
- Lower interest rates: Due to reduced risk, these loans typically carry competitive interest rates.
- Fixed repayment schedules: Most senior debt agreements include structured monthly or quarterly payments.
- Covenant protections: Loan agreements often include financial covenants that require the borrower to maintain certain metrics (e.g., debt-to-equity ratio).
- Predictable cash flow impact: Since repayments are fixed, they’re easier to budget into long-term financial plans.
Because of these traits, senior debt is ideal for companies with steady revenue streams and valuable collateral. It’s commonly used for acquisitions, expansions, or working capital needs where predictability matters.
Pros and Cons of Senior Debt
Like any financial instrument, senior debt has advantages and disadvantages. Here’s what you should consider:
Advantages:
- Lower interest costs due to secured nature
- Easier to qualify for if you have strong assets
- Stable, long-term financing with clear terms
- Preserves equity ownership since no equity dilution occurs
Disadvantages:
- Requires substantial collateral, which may limit asset use elsewhere
- Financial covenants can restrict operational flexibility
- Approval process can be lengthy and bureaucratic
- Limited availability for startups or companies without significant assets
In short, senior debt is powerful—but only if your business can meet its obligations and offer enough security to satisfy lenders.
What Is Mezzanine Debt?
Visual guide about Senior Debt Vs Mezzanine Debt
Image source: attractcapital.com
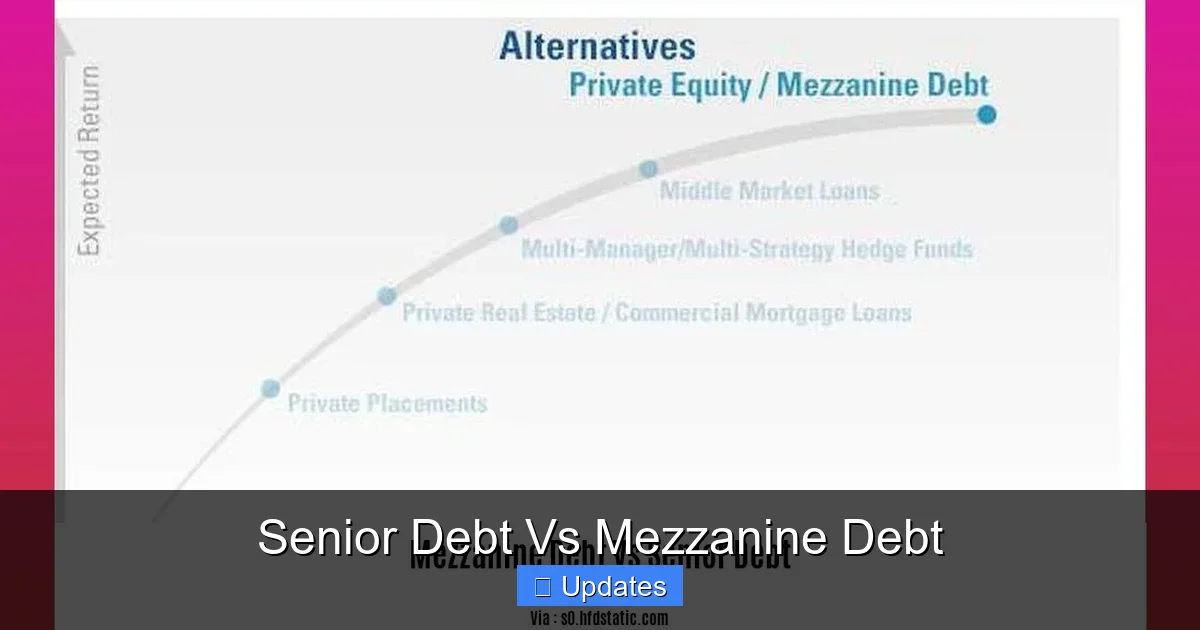
Now let’s talk about mezzanine debt—a hybrid form of financing that sits between senior debt and equity in the capital structure. Unlike senior debt, mezzanine financing is often unsecured or subordinated, meaning it’s paid after senior claims in case of default. However, it offers unique benefits: higher flexibility, potential equity participation, and the ability to bridge funding gaps.
Mezzanine debt typically carries higher interest rates than senior debt—often ranging from 12% to 18%—but less than pure equity investments. What sets it apart is that many mezzanine loans include an “equity kicker,” such as warrants or options to buy stock at a set price. This gives lenders a chance to participate in the company’s upside if it grows significantly.
For instance, a tech startup unable to secure traditional bank financing might issue mezzanine debt to fund rapid expansion. The lender receives high interest payments and also holds the option to convert part of the loan into equity if the company goes public or sells for a profit.
How Mezzanine Debt Works
Mezzanine debt is structured to give lenders downside protection similar to senior debt while offering upside potential like equity investors. Here’s how it typically flows:
- A company seeks growth capital beyond what senior debt can cover.
- The mezzanine provider lends funds, often alongside existing senior lenders.
- Interest is paid regularly (usually quarterly), but principal may be deferred until maturity or refinancing.
- If the company performs well, the lender may exercise conversion rights and become a shareholder.
- In default, repayment happens after senior debt but before equity holders.
This structure makes mezzanine debt attractive to private equity firms, growth-stage companies, and those preparing for IPOs or M&A events.
Pros and Cons of Mezzanine Debt
Advantages:
- No immediate equity dilution (if not converted)
- More flexible terms than traditional bank loans
- Can be used for buyouts, expansions, or refinancing
- Warrants increase potential return if the company succeeds
- Helps companies grow without giving up control prematurely
Disadvantages:
- Higher interest rates increase total cost of capital
- Deferred principal repayment creates future cash flow pressure
- Conversion features can lead to unexpected equity changes
- Less protection than senior debt in bankruptcy scenarios
- Often requires strong EBITDA and cash flow to qualify
Mezzanine debt shines in growth-oriented scenarios but demands careful management of repayment timing and investor expectations.
Key Differences Between Senior Debt and Mezzanine Debt
Visual guide about Senior Debt Vs Mezzanine Debt
Image source: attractcapital.com
While both serve as sources of capital, senior debt vs mezzanine debt diverge in several critical areas. Understanding these distinctions helps businesses align their financing choices with strategic goals.
Repayment Priority and Security
The biggest difference lies in priority in repayment. Senior debt enjoys top-tier status—it’s repaid first from available assets. Mezzanine debt ranks below it, meaning it’s only paid after all senior obligations are met. This affects recovery rates in distress situations.
Security is another major contrast. Senior debt is almost always secured by collateral, providing concrete recourse for lenders. Mezzanine debt may be unsecured or rely on “soft” collateral like intellectual property or future cash flows, increasing risk for providers.
Cost and Structure
Interest costs reflect risk levels. Senior debt averages 4%–9%, depending on creditworthiness and market conditions. Mezzanine debt, due to its subordinate nature, typically ranges from 12%–18%, sometimes higher.
Structurally, senior debt follows standard amortization schedules. Mezzanine loans often feature bullet payments—where most principal is due at maturity—alongside interest-only periods. This delays large cash outflows, beneficial for growing firms.
Investor Rights and Flexibility
Lenders in senior debt enjoy strong contractual protections—covenants, reporting requirements, and default triggers. Mezzanine providers also impose covenants but place greater emphasis on performance milestones and exit strategies.
Flexibility is where mezzanine excels. It can be tailored to fit complex transactions, including leveraged buyouts or pre-IPO funding rounds. Senior debt, while reliable, tends to follow rigid bank underwriting standards.
Use Cases and Suitability
Consider this comparison table for clarity:
| Feature | Senior Debt | Mezzanine Debt |
|———————–|————————————–|—————————————-|
| Best For | Stable cash flow, asset-rich firms | Growth-stage, pre-IPO companies |
| Collateral | Strong (real estate, equipment) | Weak or none; may use IP |
| Interest Rate | 5%–9% | 12%–18%+ |
| Repayment | Amortizing | Often bullet (lump sum at end) |
| Equity Participation | No | Yes (via warrants/options) |
| Bankruptcy Priority | First | Second |
Use senior debt when you need reliable, low-cost funding with predictable terms. Choose mezzanine debt when you’re scaling fast, lack sufficient collateral, or want to preserve equity until exit.
When to Choose Senior Debt Over Mezzanine Debt
Visual guide about Senior Debt Vs Mezzanine Debt
Image source: wavesold.com
Deciding between senior debt vs mezzanine debt isn’t just about cost—it’s about alignment with your business model. Here are scenarios where senior debt makes more sense:
You Have Strong Cash Flow and Assets
If your company generates consistent revenue and owns valuable physical assets, banks will likely approve senior debt easily. Examples include retail chains with prime real estate or manufacturers with heavy machinery. These businesses can pledge collateral confidently, reducing lender risk.
You Need Predictable Financing Terms
Senior debt offers fixed payment schedules and transparent covenants. For operations requiring budget stability—like franchise networks or utility services—this predictability prevents surprises during downturns.
You Want to Avoid Equity Dilution
Since senior debt doesn’t involve equity conversion, founders retain full ownership. This matters for family-owned businesses or founders wary of losing control.
However, even with strong fundamentals, mezzanine debt might still be preferable if you’re planning a major acquisition or restructuring that exceeds senior lending limits.
When to Consider Mezzanine Debt
Mezzanine financing fills a niche where traditional debt falls short. Consider it when:
Your Company Is Growing Rapidly
Startups and scale-ups often hit the ceiling of what banks will lend based on collateral alone. Mezzanine providers look beyond balance sheets, focusing instead on EBITDA growth, market share, and scalability.
You’re Preparing for an Exit Event
Private equity firms frequently use mezzanine debt to fund leveraged buyouts or support companies before IPOs. The combination of high interest and equity kicker aligns incentives toward successful exits.
Collateral Is Limited but Cash Flow Is Strong
Tech companies, SaaS platforms, or service-based businesses may lack physical assets but generate robust recurring revenue. Mezzanine lenders accept intangible value—like customer contracts or software licenses—as justification for loans.
You Need Bridge Financing
Sometimes, a temporary gap exists between Series B funding and Series C. Mezzanine debt can bridge this window, allowing time to finalize larger rounds without rushing.
In essence, mezzanine debt acts as a strategic tool for high-potential ventures willing to trade higher cost for flexibility and growth acceleration.
Practical Tips for Structuring Your Financing Mix
Balancing senior debt vs mezzanine debt requires thoughtful planning. Here’s how to optimize your capital stack:
Layer Your Debt Strategically
Most healthy companies use a mix: senior debt covers baseline needs (working capital, capex), while mezzanine bridges growth initiatives. Avoid over-leveraging—too much mezzanine increases default risk if revenues dip.
Negotiate Conversion Terms Carefully
If your mezzanine agreement includes equity conversion, clarify valuation caps and vesting schedules. Unfavorable terms could dilute founders unfairly during early-stage exits.
Monitor Covenant Compliance
Both debt types come with covenants. Set up internal dashboards to track ratios like interest coverage or leverage. Proactive monitoring prevents technical defaults that trigger penalties.
Plan for Refinancing Early
Bullet payments on mezzanine loans create lump-sum obligations. Begin discussions with lenders 12–18 months before maturity to explore rollover options or new financing.
Work With Experienced Advisors
Legal and financial professionals familiar with capital structures can help navigate complexities—especially around security interests, cross-default clauses, and tax implications.
Remember: there’s no one-size-fits-all answer. Your choice should reflect your business lifecycle, risk appetite, and long-term vision.
Real-World Examples: How Companies Use These Debt Types
Let’s look at two contrasting cases:
Case Study 1: Regional Bank Expansion (Senior Debt)
A regional bank in the Midwest sought to open five new branches. With strong deposit bases and owned properties, it qualified for $50 million in senior debt at 6.5%. The collateral included branch buildings and ATM networks. Fixed monthly payments fit neatly into projected cash inflows from increased lending activity. No equity was issued, preserving founder control.
Case Study 2: SaaS Startup Scaling Up (Mezzanine Debt)
A cloud-based CRM startup had $20M ARR but limited assets. Unable to secure traditional loans, it raised $15 million via mezzanine financing at 14% interest plus 5% equity warrants. Funds fueled R&D and sales hiring. Three years later, acquired by a larger player, the mezzanine provider exercised warrants and earned outsized returns—while the founders kept majority ownership post-acquisition.
These examples show how context shapes optimal financing decisions.
Common Misconceptions About Senior and Mezzanine Debt
Despite widespread use, misconceptions abound:
- Myth: Mezzanine debt is always riskier than senior debt.
Truth: While subordinate, mezzanine providers conduct rigorous due diligence and often require higher returns—not just because of risk, but because of structural constraints. - Myth: You can’t refinance mezzanine debt.
Truth: Many mezzanine lenders allow rollovers or replacements with new investors, especially if performance targets are met. - Myth: Senior debt is only for large corporations.
Truth: Small and mid-sized businesses with solid collateral (e.g., franchisees with prime locations) regularly access senior debt. - Myth: Mezzanine debt dilutes equity immediately.
Truth: Only upon conversion does equity impact occur—many companies delay this through negotiated terms.
Clarifying these myths helps avoid costly missteps.
Conclusion: Making the Right Choice for Your Business
Choosing between senior debt vs mezzanine debt hinges on your company’s stage, assets, growth ambitions, and risk tolerance. Senior debt offers safety, affordability, and predictability—ideal for established players. Mezzanine debt provides agility, growth alignment, and exit synergy—suited for ambitious scaling.
Neither is universally superior. The best capital stacks combine both strategically. Consult advisors, model scenarios, and prioritize long-term sustainability over short-term convenience.
Whether you’re building a legacy or chasing disruption, understanding these financing tools empowers smarter decisions. And remember: financing isn’t just about money—it’s about shaping your company’s future.
For more insights into financial strategies tailored to your industry, explore our related guides on [Albertsons To Offer 600M Senior Notes To Refinance 2026 Debt](https://seniorsprotalk.com/albertsons-to-offer-600m-senior-notes-to-refinance-2026-debt/) and [What Is The Senior Private Debt Push Down Initiative Program](https://seniorsprotalk.com/what-is-the-senior-private-debt-push-down-initiative-program/). These resources dive deeper into real-world applications of senior financing concepts.
Frequently Asked Questions
Is senior debt safer than mezzanine debt?
Yes, senior debt is generally safer because it has first priority in repayment and is often secured by collateral. In bankruptcy, senior lenders get paid before mezzanine holders, reducing their risk exposure significantly.
Can mezzanine debt convert to equity?
Yes, many mezzanine loan agreements include conversion rights—such as warrants or options—that allow lenders to exchange part of the debt into company equity, usually at a predetermined price.
What industries commonly use mezzanine debt?
Industries with high-growth potential but limited physical assets—like technology, SaaS, and professional services—often rely on mezzanine debt. It’s also popular among private equity-backed companies preparing for exits.
How does interest rate compare between senior and mezzanine debt?
Senior debt typically carries lower interest rates (5%-9%), while mezzanine debt is more expensive (12%-18%+). The difference reflects the higher risk and subordinate position of mezzanine financing.
Do I need collateral for mezzanine debt?
Not necessarily. While some mezzanine loans are secured, many are unsecured or rely on intangible assets like intellectual property or future cash flows. Lenders assess strength in other areas, such as EBITDA and growth trajectory.
Can I use both senior and mezzanine debt together?
Absolutely. Most companies layer their capital stack with senior debt for core operations and mezzanine debt for growth initiatives. Just ensure total leverage remains manageable and covenants don’t conflict.