
Senior Circuit Breaker Credit Massachusetts


Adjustable Bed Wedge Pillow

Glucose Monitor Kit

Toilet Seat Bidet Attachment
The Senior Circuit Breaker Credit in Massachusetts helps low- and moderate-income seniors and disabled residents lower their property taxes. This program provides direct tax relief based on income, age, and homeownership status. Eligible applicants may receive a credit that reduces their annual property tax bill significantly. Understanding the rules and applying early ensures you don’t miss out on vital financial support.
If you’re a senior living in Massachusetts, you’ve probably noticed how much your property taxes have climbed over the past few years. Between rising home values and inflation, many older adults find it harder to keep up with annual bills. That’s where the Senior Circuit Breaker Credit comes in—a lifeline created specifically to ease the burden of property taxation for eligible residents. This program isn’t just helpful; for thousands of seniors across the state, it’s a critical source of financial stability.
But here’s the thing: even though this credit is available statewide, many qualified seniors don’t apply—either because they don’t know about it or assume they won’t qualify. The truth? If you’re a homeowner over 65 (or disabled), meet income guidelines, and live in your own home, you might be entitled to hundreds—even thousands—of dollars in tax relief. In this guide, we’ll walk you through everything you need to know: who qualifies, how much you could save, where to apply, and why acting fast matters. Let’s get started.
Key Takeaways
- The Senior Circuit Breaker Credit is a state-funded program designed to help Massachusetts seniors and disabled individuals afford rising property taxes.
- Income limits apply: Applicants must meet strict household income thresholds based on age, disability status, and family size to qualify.
- Property value matters: Only owner-occupied homes are eligible, and the credit amount depends on both income and assessed property value.
- Application timing is crucial: File by the deadline—usually March 1—to ensure timely processing and tax relief for the current year.
- You may qualify for back credits: If you missed a previous year, you can often file a late application under certain conditions.
- Local assessors play a role: Your town’s assessor office handles applications and provides forms specific to your municipality.
- Combining benefits is possible: Some seniors also qualify for local or federal programs like Massachusetts Senior Circuit Breaker Tax Credit, maximizing overall savings.
📑 Table of Contents
- What Is the Massachusetts Senior Circuit Breaker Credit?
- Who Qualifies for the Senior Circuit Breaker Credit in MA?
- How Much Can You Save With the Senior Circuit Breaker Credit?
- How to Apply for the Senior Circuit Breaker Credit
- Can You Combine This Credit With Other Programs?
- State vs. Local Variations in Massachusetts
- What Happens If You Missed the Deadline?
- Frequently Asked Questions About the Senior Circuit Breaker Credit
What Is the Massachusetts Senior Circuit Breaker Credit?
At its core, the Senior Circuit Breaker Credit is a targeted tax reduction program administered at the municipal level but funded by the state of Massachusetts. It was established to prevent seniors and disabled residents from being displaced from their homes due to unaffordable property taxes. Think of it as a “circuit breaker”—a safety feature that kicks in when expenses spike beyond what’s reasonable.
Unlike standard property tax deductions, this credit directly lowers your tax bill dollar-for-dollar. For example, if your annual property tax is $3,000 and you qualify for a $1,500 credit, your final payment drops to $1,500. Best of all, the credit amount adjusts based on your income: the lower your income, the higher the potential benefit.
This program operates slightly differently than federal or national senior tax credits. Instead of a one-size-fits-all approach, each Massachusetts town sets its own application process and sometimes even supplemental local credits. However, all follow the same basic framework defined by the Massachusetts Department of Revenue (DOR).
How Does It Work?
The mechanics are straightforward. Each year, homeowners submit an application to their local assessor’s office. They provide proof of age (like a driver’s license or birth certificate), income documentation (tax returns, Social Security statements), and proof of residency. Once reviewed, the assessor calculates your eligibility using formulas that compare your household income to your home’s assessed value.
If approved, the credit is applied to your next property tax bill—often reducing it by 30% to 70%, depending on your situation. Importantly, unlike refundable tax credits, you don’t receive cash if the credit exceeds your liability—but you still save real money.
Who Qualifies for the Senior Circuit Breaker Credit in MA?
Qualifying isn’t automatic—there are clear rules. But if you fall into any of these categories, you’re likely on solid ground:
Age Requirement: You must be 65 years or older by December 31 of the tax year.
Disability Status: Disabled individuals under 65 may also qualify if they have a permanent physical or mental impairment limiting major life activities.
Residency & Ownership: You must own and occupy your primary residence in Massachusetts. Second homes, rental properties, or vacation homes don’t count.
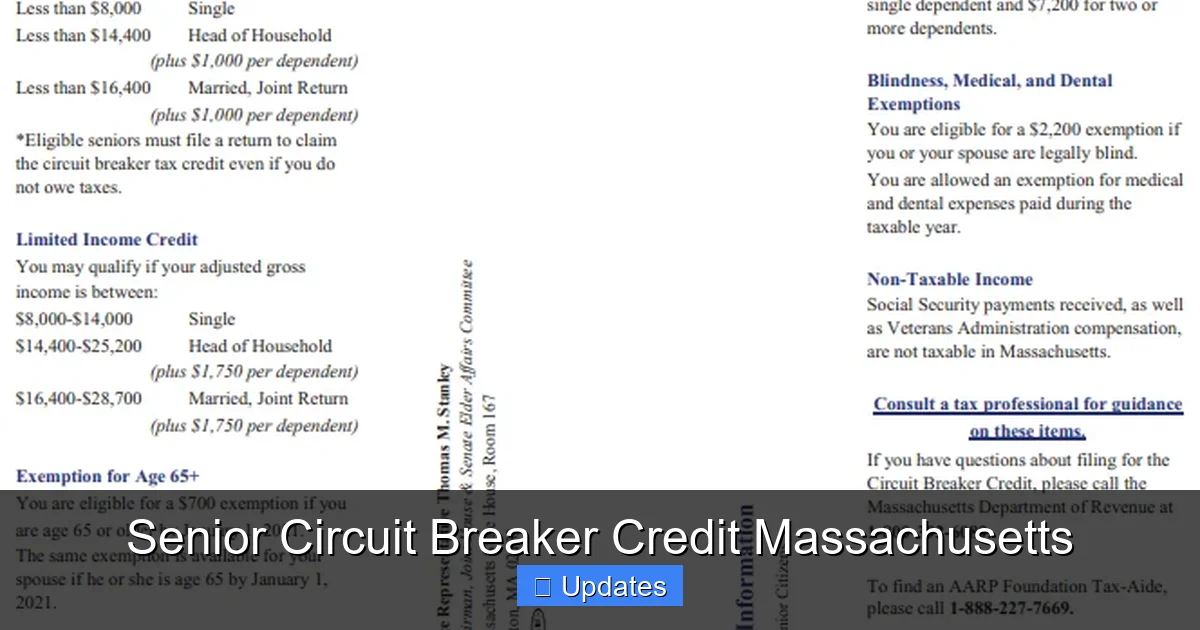
Income Limits: These vary by household size and age. As of 2024, single applicants over 80 must have incomes below $52,000; those aged 65–79 must stay under $45,000. Couples filing jointly face higher thresholds—up to $65,000 for two people over 80.
It’s important to note that “income” includes wages, pensions, Social Security, retirement accounts, investment gains, and more. Excluded items typically include Supplemental Security Income (SSI) and veterans’ disability compensation.
Example Scenario
Let’s say Mary is 72 and lives alone in Springfield. Her annual income is $40,000 from a pension and part-time work. Her home is assessed at $250,000, and her annual property tax is $3,600. Because she meets the age and income requirements, she applies through her city assessor and receives a $1,800 credit. Her net tax payment becomes $1,800—a full 50% reduction. That extra $1,800 could go toward groceries, medical co-pays, or simply peace of mind.
How Much Can You Save With the Senior Circuit Breaker Credit?
Savings depend heavily on your income level and home value. Generally speaking:
- Low-income seniors (under 60% of area median income) often see the largest cuts—sometimes reducing their tax bill by over half.
- Middle-income applicants may still save 20%–40%, especially in high-tax towns like Cambridge or Brookline.
- Higher-income qualifiers might only get modest reductions, but every bit helps.
For context, the maximum credit in recent years has ranged from $1,200 to $2,400 annually per household. Towns can also add their own supplemental credits—like Worcester’s additional $500 boost—so check with your local office.
To estimate your potential savings, use the DOR’s online calculator or request a preliminary assessment from your assessor. Keep in mind that credits are retroactive—if you were eligible last year but didn’t apply, you can usually claim it now.
Real-World Impact
Consider Robert, a 78-year-old widow in Lowell. After losing his spouse, his fixed income dropped to $38,000. Without the circuit breaker, his $4,200 annual tax bill would consume nearly 11% of his budget. Thanks to the program, he received a $2,100 credit, slashing his payment to $2,100—less than 6% of his income. He used the saved funds to install grab bars in his bathroom and pay for prescription drugs.
These stories aren’t rare. According to Mass DOR data, over 12,000 seniors claimed the credit in 2023 alone, saving millions collectively.
How to Apply for the Senior Circuit Breaker Credit
Applying seems intimidating, but it’s simpler than you think. Here’s your step-by-step roadmap:
- Gather Documents: Birth certificate or passport, Social Security card, most recent federal tax return, proof of income (pension statements, bank interest reports), and your property deed or mortgage statement.
- Contact Your Local Assessor: Visit your town’s website or call the assessor’s office. Most offer downloadable PDF forms or accept emailed submissions.
- Submit Before the Deadline: The cutoff is almost always March 1 for the prior tax year. Late filings are accepted in limited circumstances—like if you turned 65 recently or had a medical emergency.
- Follow Up: Ask for a confirmation number and estimated processing time. Some towns issue decisions within weeks; others take months.
Pro tip: Don’t wait until February! Forms sometimes require notarization or extra paperwork, and processing delays happen.
Common Mistakes to Avoid
Many applicants make simple errors that delay approval:
- Missing income details: Even small side incomes matter. Report all sources, including child support or alimony.
- Using outdated forms: Always download the latest version from your town’s site—not third-party websites.
- Failing to sign: Unsigned forms are automatically rejected.
If denied, request a written explanation. You can appeal within 30 days with additional evidence.
Can You Combine This Credit With Other Programs?
Absolutely! Many seniors stack multiple benefits for maximum impact. For instance:
- Chapter 62C Tax Credit: Available for renters in certain municipalities—but only if you don’t own your home.
- Veterans Benefits: If you’re a veteran, you may qualify for additional property tax exemptions regardless of income.
- Low-Income Home Energy Assistance Program (LIHEAP): Helps cover heating costs—another layer of support.
- Community Action Agencies: Organizations like Greater Springfield Senior Services offer case management to help navigate all available resources.
Just remember: you can’t double-dip on the same expense. But combining credits, exemptions, and services multiplies your savings.
Case Study: Maximizing Benefits
Elena, a 70-year-old veteran in Framingham, applied for the Senior Circuit Breaker Credit and also enrolled in the Callahan Senior Center’s assistance program. She learned about a local utility discount and a property tax deferral option. Combined, these reduced her annual housing costs by nearly $3,000—freeing up cash for travel and hobbies.
This illustrates why it pays to explore every angle. A quick chat with your assessor or a senior center advisor can open doors you didn’t know existed.
State vs. Local Variations in Massachusetts
While the core program is uniform, individual towns tweak parameters. For example:
- Boston offers a supplemental $1,000 credit for seniors over 80 with incomes under $40,000.
- Cambridge allows deferral of unpaid credits to future tax bills—helping avoid sudden spikes.
- Springfield partners with nonprofits to help fill out complex forms.
Always verify details locally. Your neighbor’s experience doesn’t guarantee yours—towns update rules annually based on state funding.
Why Local Knowledge Matters
Take Plummer Place in Northbridge: this facility not only hosts the senior center but also distributes application packets and hosts workshops. Staff there know which forms are easiest to complete and can flag red flags before submission. Similar resources exist across the state—don’t hesitate to reach out.
What Happens If You Missed the Deadline?
Life happens. Maybe you turned 65 last December and forgot to apply. Or perhaps you were hospitalized. The good news: late applications are often accepted.
According to Mass DOR policy, you can file up to three years after the deadline if:
- You were eligible during that period,
- You have valid justification (medical records, death certificates, etc.),
- Your town agrees to process it.
Start gathering documents immediately. Include a cover letter explaining your delay—many assessors are understanding if you show good faith.
Emergency Circuits: When Speed Counts
In rare cases, towns offer expedited reviews for urgent situations. If you’re facing eviction or utility shutoff due to tax debt, contact your assessor ASAP. Mention “emergency hardship” when applying—it sometimes triggers faster handling.
Frequently Asked Questions About the Senior Circuit Breaker Credit
Is the Senior Circuit Breaker Credit only for homeowners?
Yes. You must own and occupy your primary residence in Massachusetts. Renters may qualify for separate programs like Chapter 62C in certain cities, but not the standard Senior Circuit Breaker Credit.
Visual guide about Senior Circuit Breaker Credit Massachusetts
Image source: repdaverogers.com
Visual guide about Senior Circuit Breaker Credit Massachusetts
Image source: blogger.googleusercontent.com
Visual guide about Senior Circuit Breaker Credit Massachusetts
Image source: blogger.googleusercontent.com
Do I need to reapply every year?
Yes. Eligibility resets annually based on income and age. However, once approved, some towns allow streamlined renewals—ask your assessor about auto-renewal options.
Can my spouse and I both apply separately?
No. Married couples must file jointly. Filing separately disqualifies you from the credit entirely.
Will the credit affect my Medicaid or SNAP benefits?
No. The Senior Circuit Breaker Credit is not counted as income for means-tested programs like Medicaid or food stamps.
What if my town doesn’t participate?
All Massachusetts cities and towns must offer the basic Senior Circuit Breaker Credit as mandated by state law. If yours doesn’t, contact the Massachusetts Division of Elder Affairs for intervention.
Are there income exclusions I should know about?
Generally, yes. SSI, VA disability compensation, and certain retirement benefits are excluded from gross income calculations. Always disclose all income, but rest assured that protected benefits won’t push you over the limit.
Frequently Asked Questions
Is the Senior Circuit Breaker Credit only for homeowners?
Yes. You must own and occupy your primary residence in Massachusetts. Renters may qualify for separate programs like Chapter 62C in certain cities, but not the standard Senior Circuit Breaker Credit.
Do I need to reapply every year?
Yes. Eligibility resets annually based on income and age. However, once approved, some towns allow streamlined renewals—ask your assessor about auto-renewal options.
Can my spouse and I both apply separately?
No. Married couples must file jointly. Filing separately disqualifies you from the credit entirely.
Will the credit affect my Medicaid or SNAP benefits?
No. The Senior Circuit Breaker Credit is not counted as income for means-tested programs like Medicaid or food stamps.
What if my town doesn’t participate?
All Massachusetts cities and towns must offer the basic Senior Circuit Breaker Credit as mandated by state law. If yours doesn’t, contact the Massachusetts Division of Elder Affairs for intervention.
Are there income exclusions I should know about?
Generally, yes. SSI, VA disability compensation, and certain retirement benefits are excluded from gross income calculations. Always disclose all income, but rest assured that protected benefits won’t push you over the limit.